- Property Tax Management

Non-Primary Residence Surcharge (Pieds-à-Terre Tax)
Received a surcharge notice? Check your property in MGNY’s app using the address or BBL. Start with the free public DOF record lookup and available surcharge estimate, then sign in for review and document steps. Prefer to talk? Call (212) 343-1111 with your notice, ownership details and available residency records.
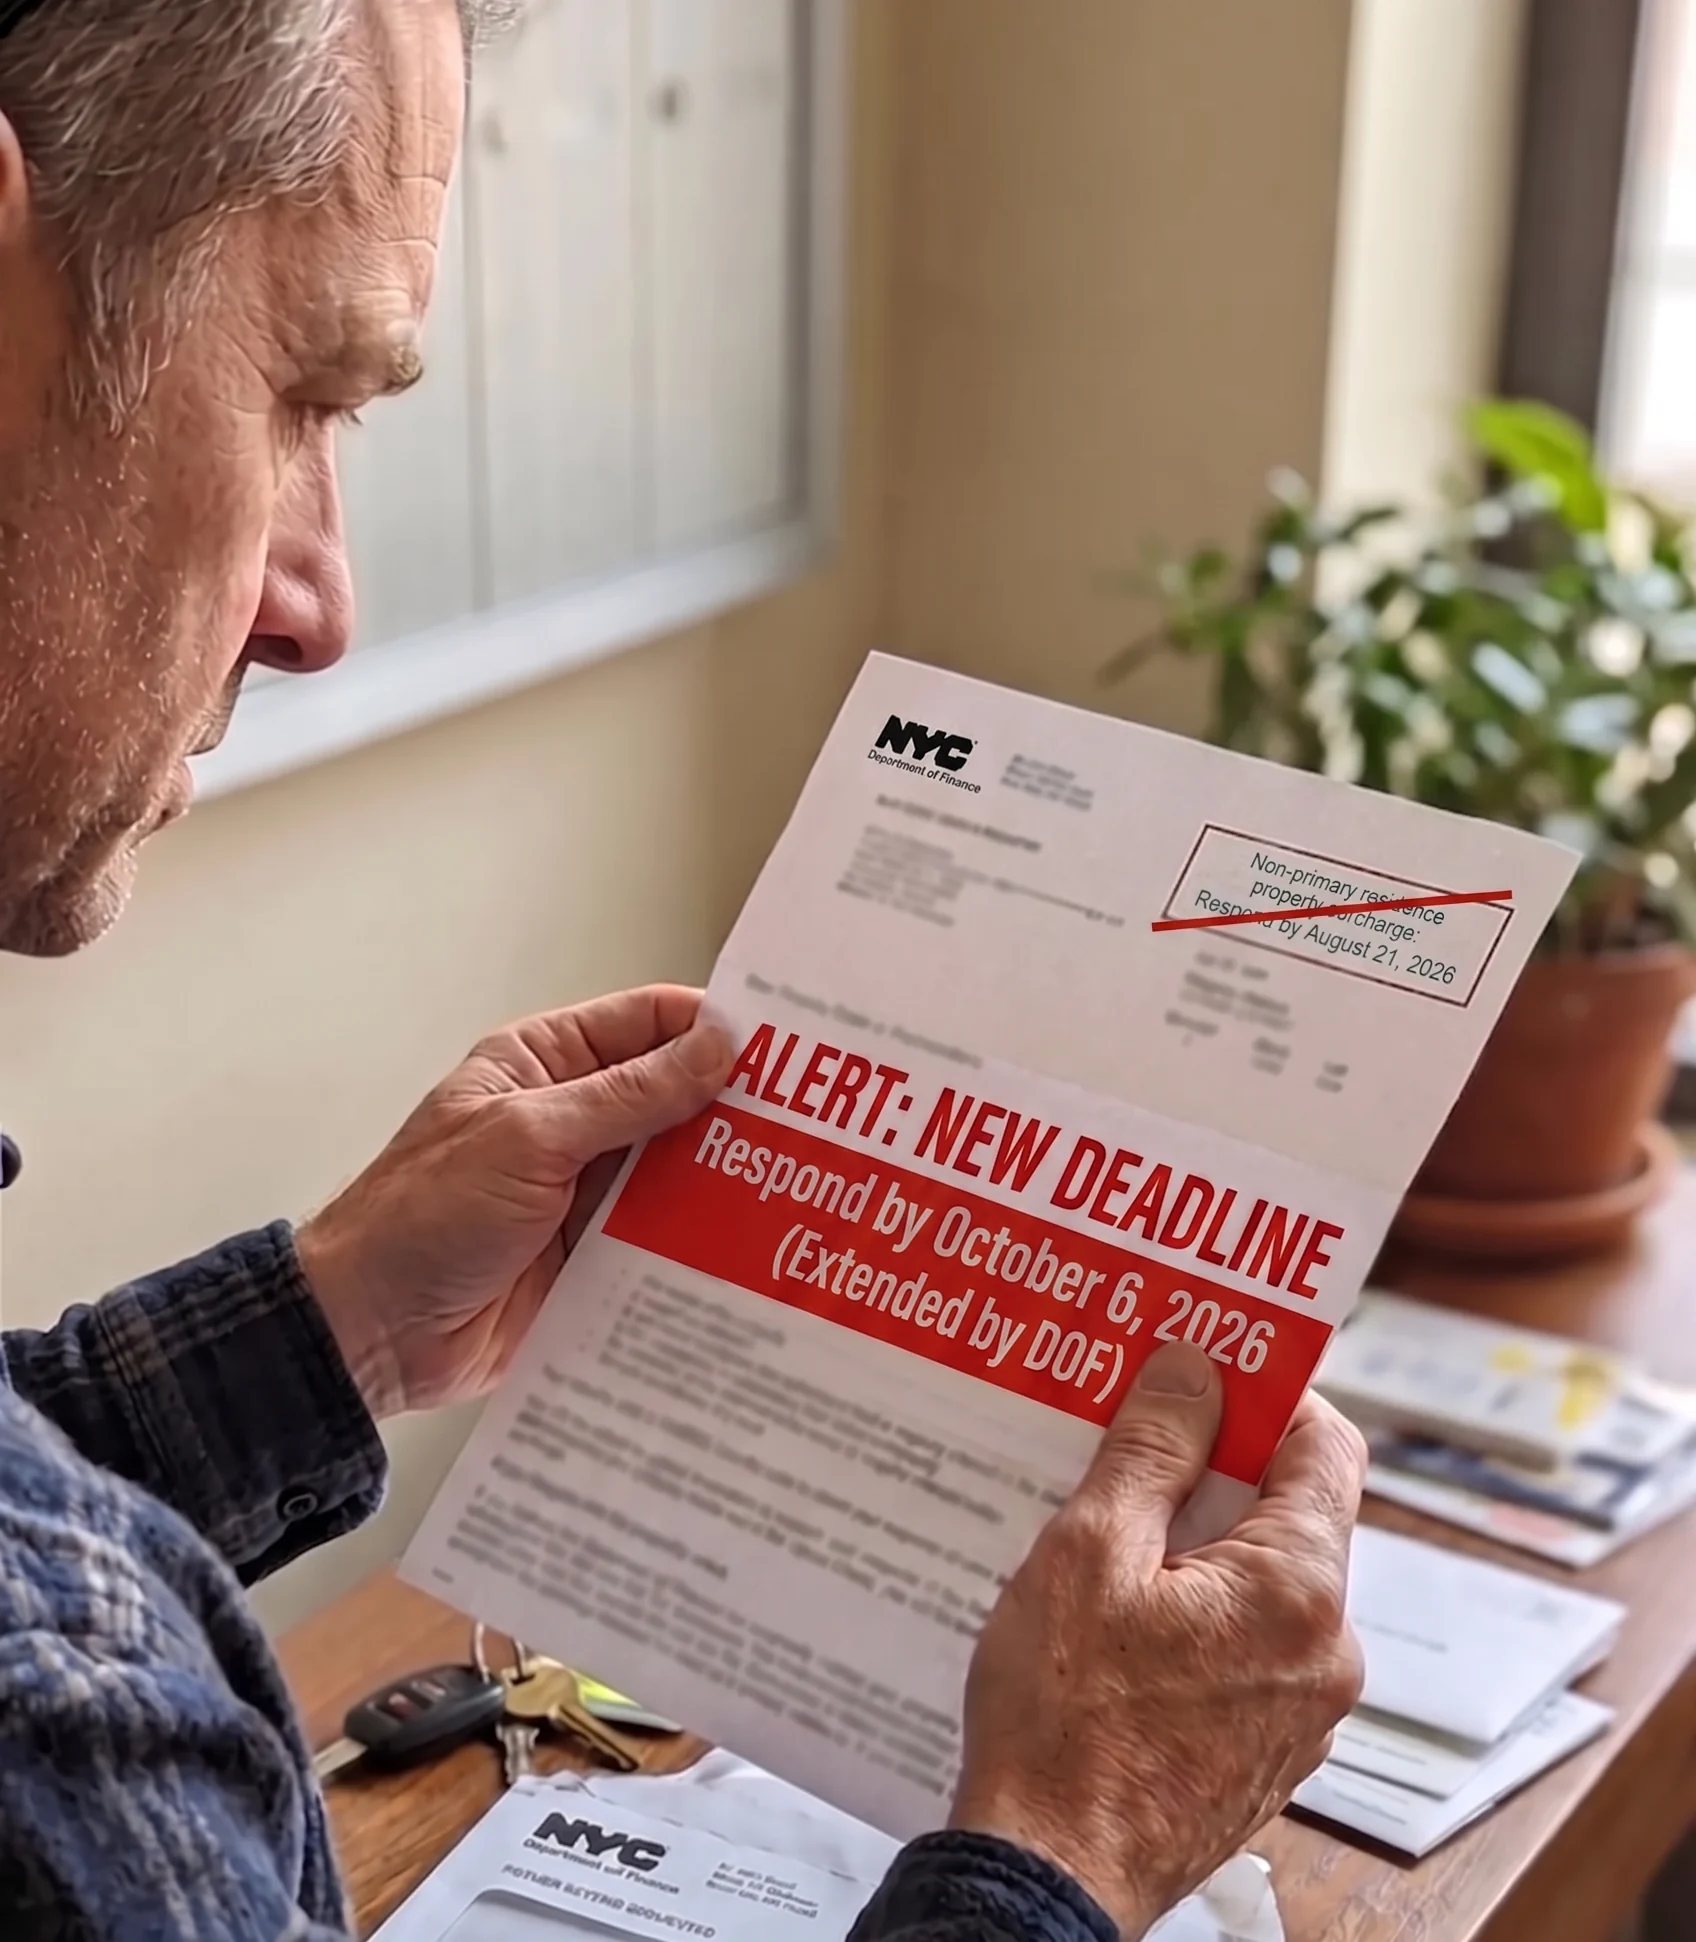
A notice from the New York City Department of Finance (DOF) means its records did not confirm a qualifying primary resident for your property. Receiving a notice does not by itself establish that the surcharge is due. For the 2026/27 and 2027/28 tax years, the published rates are 4.00%, 5.25% or 6.50% of DOF market value for covered condos and co-ops from $1 million, and 0.80%, 1.05% or 1.30% for covered one- to three-family homes from $5 million. The Department of Finance’s page says the deadline to apply for an exemption for tax year 2026-27 was October 13, 2026. The notices originally stated August deadlines, and the date moved three times.
What is the surcharge called?
Three names, one surcharge: the letter says non-primary residence property surcharge, New Yorkers say pied-a-terre tax, and law firms writing to their clients have shortened that to the PAT tax. Whichever name you arrived with, this page is about the same charge.
Who is exempt from the surcharge?
The surcharge is not automatic. An exemption may apply if the property is the primary residence of a qualifying owner, tenant or subtenant, majority interest holder, qualifying immediate family member, or the sole beneficiary or beneficiaries of a trust. For the 2026/27 tax year, primary residence is measured as of January 5, 2026. A tenant or subtenant must be a natural person occupying under a bona fide, arms-length lease of at least one year. An individual cannot establish covered-owner residency through a multi-tier business ownership chain; that restriction does not by itself decide whether a separate tenant-based exemption applies. Ownership, trust and occupancy documents must support the particular claim. Intended future occupancy is not evidence of primary residence on the applicable date.
How does MGNY challenge the surcharge?
MGNY reviews surcharge notices and helps prepare exemption applications or Tax Commission appeals where appropriate. DOF decides exemption applications; surcharge market-value challenges go to the Tax Commission on Form TC107. An initial primary-residence challenge at the Tax Commission must also challenge market value, and DOF defers to the Commission on residency. An appeal of DOF’s final primary-residence determination is a separate route and does not itself require a value challenge. A later deadline for that final-determination appeal does not extend the market-value deadline. For the 2026/27 and 2027/28 rates, a supported reduction below a condo or co-op tier boundary of $1 million, $3 million or $5 million, or a home boundary of $5 million, $15 million or $25 million, can lower or eliminate the surcharge. A reduction is not guaranteed.
Why does the Department of Finance record matter?
The property description, ownership record and valuation evidence help identify what needs review. A difference in square footage or use does not, by itself, prove that the surcharge value is excessive. The claim must be supported under the applicable valuation rules. Where a building also has an RPIE filing, its income and expense records should be considered consistently with any appeal evidence.
What comes after the October 13, 2026 deadline?
Use our surcharge rate explainer, property lookup and the notice guide at npsurcharge.com to prepare for a review. These resources do not establish exemption eligibility. The surcharge explainer covers the response process; our property-list guide explains the roll and security-code notice, and our litigation background provides further context. Call (212) 343-1111 with your notice, ownership details and available residency evidence. MGNY can review whether an appeal route applies and agree the filing scope with you. On September 29, 2026 a court ordered the mailed surcharge notices cancelled. On November 4, 2026 the Appellate Division reversed that ruling and dismissed the case. The Tax Commission’s page lists Form TC107 as the other way to appeal DOF’s determination, due March 1, 2027 for Class 2 and March 15, 2027 for Class 1, or 30 days after a DOF final determination if that is later, and DOF’s page says the Tax Commission considers residency only if you are also challenging the property value.
New to the term itself? The meaning of pied-à-terre, and what counts as one in the city’s eyes, is covered separately.
What should you have ready for a notice review?
- The notice and property record: the address, borough-block-lot, property type and Department of Finance market value.
- The ownership structure: whether title is held by an individual, entity, trust or cooperative corporation.
- The claimed primary resident: the relationship to the owner and available evidence of residence for the relevant date.
- Prior action: any exemption submission, confirmation, denial or appeal correspondence already received.
Begin with those details. The documents required for a filing depend on the exemption claimed and the ownership arrangement. Review the current Department of Finance requirements before submitting, and discuss sensitive documents with our team before sending them through a general enquiry form.
Exemption deadline checked November 10, 2026: the Department of Finance’s page says it was October 13, 2026. A separate determination or appeal can have its own requirements; see the Tax Commission’s current surcharge appeal instructions and our Form TC107 guide for the appeal process.
 All Property Tax Services